Al-Attiyah Foundation | Al-Attiyah Foundation | Tuesday, August 04, 2026 | 12:00 PM UTC
Introduction
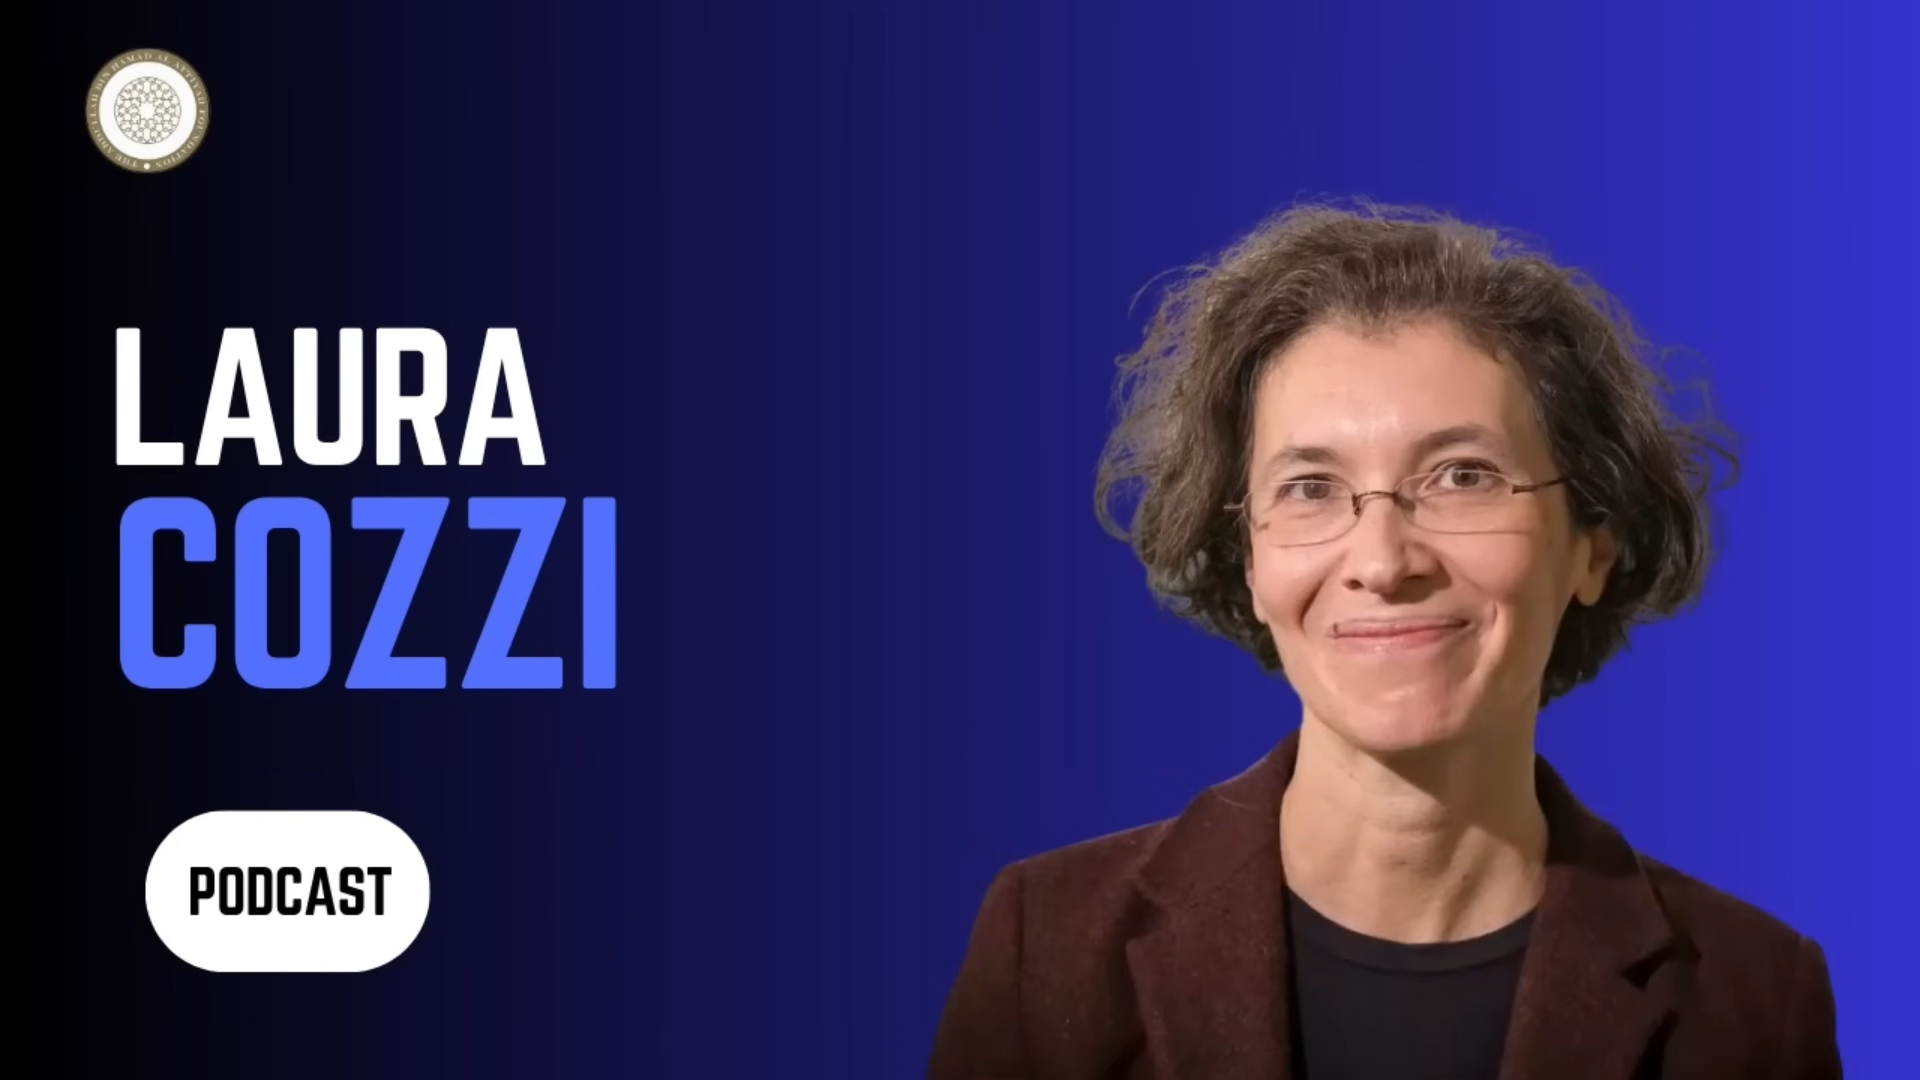
In the latest episode of the Al‑Attiyah Foundation Podcast, Laura Cozzi, Director of Sustainability, Technology and Outlooks at the International Energy Agency (IEA), sits down to discuss a series of seismic shifts that are redefining the world’s energy landscape. Cozzi brings a unique blend of policy expertise, technical insight, and forward‑looking analysis, offering listeners a panoramic view of how current geopolitical events, rapid advances in artificial intelligence, and accelerating climate commitments are converging at a critical juncture. The conversation not only explores the Middle East’s evolving role in global energy markets but also probes whether the industry is under‑estimating the future demand for AI‑driven solutions and what that means for climate action and international cooperation.
What makes this dialogue especially compelling is its timing. The world is grappling with supply‑chain disruptions, volatile oil prices, and a renewed urgency around net‑zero targets. Against this backdrop, Cozzi’s insights provide a roadmap for policymakers, investors, and industry leaders who must navigate uncertainty while capitalising on emerging opportunities.

Listen to the Podcast on Apple, Spotify, YouTube via Al Attiyah Foundation website
Industry Overview
The global energy sector stands at the intersection of three powerful forces: the transition to low‑carbon sources, the digital transformation of energy systems, and shifting geopolitical dynamics that reshape supply and demand patterns. Over the past decade, renewable generation has grown from a niche component to a cornerstone of many national grids, with solar and wind capacity increasing by more than 150% worldwide. Simultaneously, natural gas has cemented its role as a bridge fuel, offering flexibility and lower emissions compared to coal.
Yet, despite the rapid uptake of renewables, the International Energy Agency projects that total primary energy demand will continue to rise through 2030, driven largely by emerging economies in Asia and the Middle East. This paradox—rising demand alongside decarbonisation ambitions—creates a complex operating environment for traditional oil‑and‑gas exporters, who must balance legacy revenue streams with diversification into cleaner technologies.
Within this macro‑environment, the IEA’s sustainability portfolio, led by Cozzi, focuses on three pillars: policy alignment, technology deployment, and outlook forecasting. By integrating climate targets with market mechanisms, the agency aims to provide a coherent narrative that aligns national energy strategies with global climate goals.
Current Market Trends
1. Geopolitical Realignments and Energy Security
The ongoing conflict in Eastern Europe, coupled with shifting alliances in the Indo‑Pacific, has amplified the importance of energy security. Nations are re‑evaluating import dependencies, prompting a surge in strategic petroleum reserves and a renewed interest in domestic production capabilities. In the Middle East, countries such as Saudi Arabia and the United Arab Emirates are leveraging their fiscal strength to invest in downstream petrochemicals, hydrogen projects, and carbon‑capture initiatives, positioning themselves as both energy suppliers and technology exporters.
2. Accelerated Adoption of AI and Digital Tools
Artificial intelligence is rapidly moving from a peripheral support function to a core driver of operational efficiency. Predictive maintenance, demand‑response optimisation, and real‑time emissions tracking are now powered by machine‑learning algorithms that can process terabytes of data in seconds. While the oil and gas sector has historically been slower to adopt AI compared to tech‑centric industries, recent pilot projects demonstrate significant cost savings—up to 15% in drilling operations and 20% in grid management.
3. Renewable Integration and Storage Innovation
Renewable penetration is reaching levels that challenge traditional grid stability. Battery storage, pumped hydro, and emerging technologies such as solid‑state batteries are being deployed at scale to smooth intermittency. The IEA’s latest outlook highlights that by 2035, storage capacity could double, driven largely by policy incentives and falling battery costs.
Key Challenges
Despite the optimism surrounding these trends, the sector faces formidable obstacles that could stall progress if left unaddressed.
- Policy Uncertainty: Inconsistent regulatory frameworks across regions create investment hesitancy. While the European Union has enacted the Green Deal, many Middle Eastern jurisdictions lack clear long‑term decarbonisation roadmaps.
- Capital Allocation: The transition requires trillions of dollars in capital. Traditional oil‑rich economies must reallocate funds from hydrocarbon projects to green infrastructure without jeopardising fiscal stability.
- Technological Gaps: Advanced AI models demand high‑quality data and robust cybersecurity measures. Energy firms often grapple with legacy IT systems that are ill‑suited for seamless integration.
- Workforce Transformation: The shift toward digital and low‑carbon operations necessitates reskilling millions of workers, a challenge compounded by regional skill shortages.
These challenges are interlinked; for example, policy ambiguity can deter investment, which in turn limits the resources available for workforce development and technology upgrades.
Opportunities and Growth Areas
Addressing the challenges opens a spectrum of growth opportunities that can be strategically leveraged.
Renewable‑Heavy Export Models
Middle Eastern nations possess abundant solar irradiance, making them ideal candidates for large‑scale renewable export projects. By developing green hydrogen hubs, countries can tap into European and Asian demand for clean energy, turning a traditional export‑centric model into a diversified, low‑carbon portfolio.
AI‑Enabled Energy Management
Companies that embed AI into asset management can achieve higher uptime, lower emissions, and improved profitability. The IEA forecasts that AI‑driven optimisation could shave up to 10% off global CO₂ emissions by 2030, a figure that underscores the technology’s strategic relevance.
Carbon Capture, Utilisation, and Storage (CCUS)
CCUS remains one of the few viable pathways for decarbonising hard‑to‑abate sectors such as cement and steel. Investment in CCUS clusters, particularly in regions with existing fossil‑fuel infrastructure, can create new revenue streams while aligning with net‑zero commitments.
Cross‑Border Energy Cooperation
Enhanced interconnection between the Middle East, North Africa, and Europe could facilitate power trade, balancing supply and demand across time zones. Such cooperation would also foster shared research and development initiatives, accelerating technology diffusion.
Technology / Innovation / Strategic Insights
Innovation is the engine that will propel the energy sector through its transformation. Below are three strategic insights drawn from Cozzi’s analysis.
- Hybrid Energy Systems – Combining renewable generation with flexible gas‑fired plants creates a resilient hybrid that can adapt to demand spikes while maintaining low emissions. The IEA’s scenario modelling shows that hybrid systems can reduce curtailment losses by up to 30%.
- Edge Computing for Real‑Time Grid Control – Deploying edge devices at substations enables instantaneous data processing, reducing latency in demand‑response actions. This technology is especially critical for integrating distributed energy resources (DERs) at scale.
- AI‑Driven Forecasting for Demand and Supply – Advanced neural networks can predict electricity demand with a margin of error under 2%, allowing utilities to optimise generation schedules and minimise reliance on fossil‑fuel peakers.
Strategically, energy firms should adopt a “dual‑track” approach: continue investing in proven low‑carbon technologies while simultaneously experimenting with breakthrough innovations. This balanced portfolio mitigates risk and ensures readiness for rapid market shifts.
Expert or Industry Perspective
Laura Cozzi emphasizes that the industry’s perception of AI demand is still nascent. “Many executives view AI as a cost centre rather than a value creator,” she notes. “When you factor in the potential for emissions reductions, operational savings, and new business models, the upside is far greater than current estimates.” She points to a recent IEA case study where an AI‑enabled predictive maintenance program reduced offshore platform downtime by 18%, translating into a 12% reduction in greenhouse‑gas intensity for the operator.
From a climate‑action standpoint, Cozzi argues that geopolitical events—such as the recent energy price spikes—have inadvertently heightened awareness of the need for diversified, resilient energy systems. “The crisis has acted as a catalyst for cooperation,” she says, citing the renewed dialogue between the European Union and Gulf Cooperation Council on joint hydrogen projects.
Regional or Global Impact
On a regional level, the Middle East’s strategic pivot toward renewables and hydrogen could reshape trade flows. By 2030, the IEA estimates that the Gulf could become a net exporter of clean energy, challenging the traditional oil‑centric export paradigm. This shift would have ripple effects on global oil markets, potentially moderating price volatility.
Globally, the integration of AI across the energy value chain promises to accelerate decarbonisation timelines. A 2024 IEA report co‑authored by Cozzi indicates that AI could enable a 0.5°C faster reduction in global temperature rise by 2050 if adopted at scale. Moreover, coordinated climate policies—spurred by recent multilateral summits—are fostering a more collaborative environment for technology sharing, financing, and standards development.
Future Outlook
Looking ahead, Cozzi envisions a multi‑phase evolution of the energy sector.
Phase 1 (2025‑2028): Consolidation and Digitalisation – Energy companies will focus on integrating AI into existing assets, standardising data platforms, and establishing carbon‑pricing mechanisms.
Phase 2 (2029‑2034): Diversification and Green Export – Nations with abundant renewable resources will scale up green hydrogen production, leveraging export corridors to Europe and Asia.
Phase 3 (2035+): Net‑Zero Integration – AI, advanced storage, and CCUS will converge to enable near‑zero‑emission energy systems, while international cooperation solidifies around shared climate goals.
Crucially, the success of each phase hinges on policy coherence, capital availability, and the willingness of industry leaders to embrace transformative technologies.
Conclusion
Laura Cozzi’s insights illuminate a pivotal moment for the global energy ecosystem. The Middle East’s strategic realignment, the under‑recognised surge in AI demand, and the heightened urgency of climate cooperation together form a triad that will dictate the sector’s trajectory for the next decade and beyond. Stakeholders who act decisively—by aligning policy, investing in innovation, and fostering cross‑regional partnerships—stand to reap both economic and environmental dividends. As the Al‑Attiyah Foundation Podcast underscores, the turning point is not a distant horizon; it is unfolding today, and the choices made now will echo through the next generation of energy markets.
